
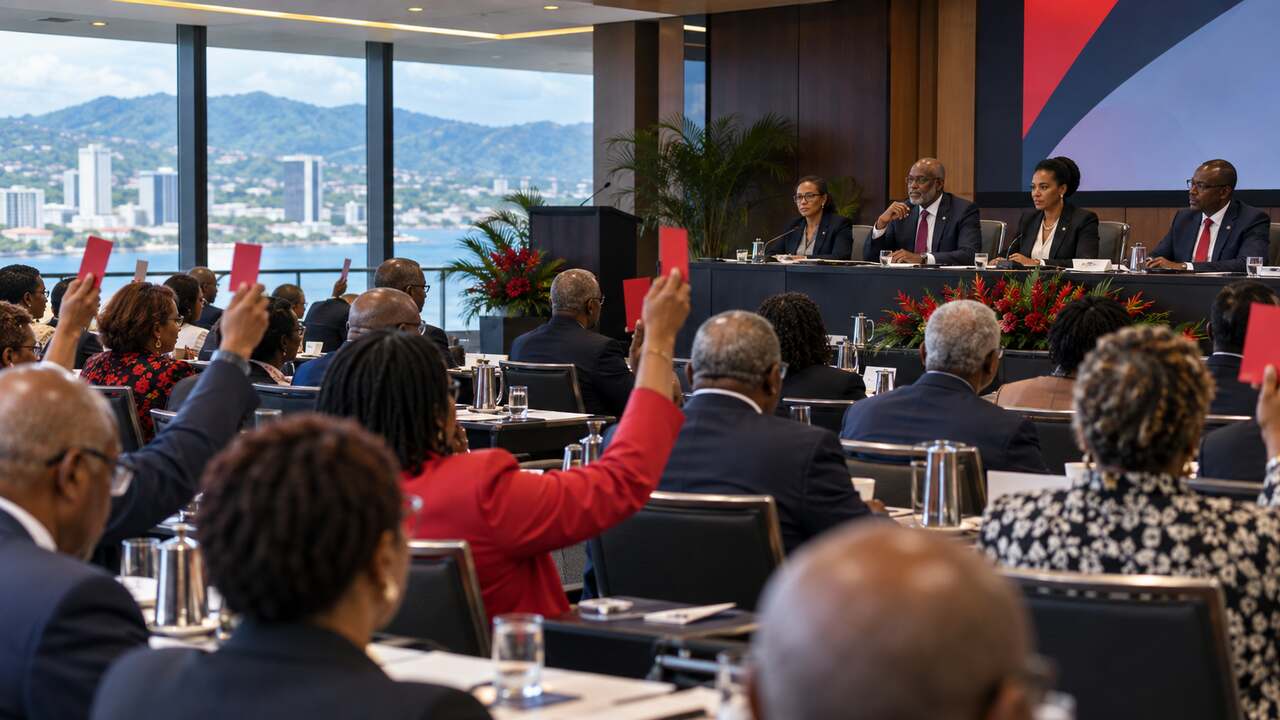

Scotia Group Jamaica’s minority shareholders have approved a plan that will take the company private. Under the revised offer, minority investors are set to receive J$75 for each ordinary stock unit, putting the value of the buyout at roughly J$63.5 billion. The vote clears a major hurdle, although the transaction still has formal closing steps ahead.
For shareholders, this is a direct money question: what should happen to the cash if the deal closes? For Jamaica, it is a market question: what happens when one of the country’s biggest listed companies disappears from the exchange?
Why the vote matters beyond Scotia
A listed company gives ordinary investors a way to own a piece of a major business. It also gives pension funds, pooled funds and local institutions a place to deploy capital. When a large company goes private, investors receive cash, but they lose one public option for future income and growth.
That matters because Jamaica’s market is already concentrated. A few large companies can influence the headline index, so the removal of a major bank can change the market’s shape even if shareholders receive an attractive premium. The exchange may look less diversified, and future investors may have fewer businesses to compare.
The cash decision for shareholders
The first mistake would be to treat the J$75 as free money. It is payment for an asset that will leave the portfolio. If the cash is needed for school fees, debt reduction, a home purchase or an emergency reserve, keeping it available may be sensible. If the money was intended for long-term growth, the investor needs a replacement plan.
The second mistake would be to rush into the next stock simply because the cash has arrived. A disciplined investor asks what the portfolio is missing: local income, global growth, liquidity, inflation protection or diversification outside one economy. The answer should determine the next move.
What the diaspora should watch
Diaspora investors often use Jamaica’s market as part of a broader Caribbean or home-country allocation. The Scotia deal is a reminder that market access can change. A company available today may not be available in the same form tomorrow. That makes it important to understand liquidity, ownership concentration, deal conditions and what happens to the cash after a takeover.
Bottom line: The Scotia vote may reward minority shareholders, but it also highlights a structural issue. Jamaica needs more investable companies, not fewer. For investors, the lesson is simple: treat a buyout as a portfolio decision, not just a headline or a cheque.