

The oil market has delivered a fresh warning to Caribbean households: a price shock can travel a long way before it reaches your electricity bill, supermarket receipt or next airline booking. Friday’s jump in crude is another reason to keep an eye on costs beyond the petrol pump.
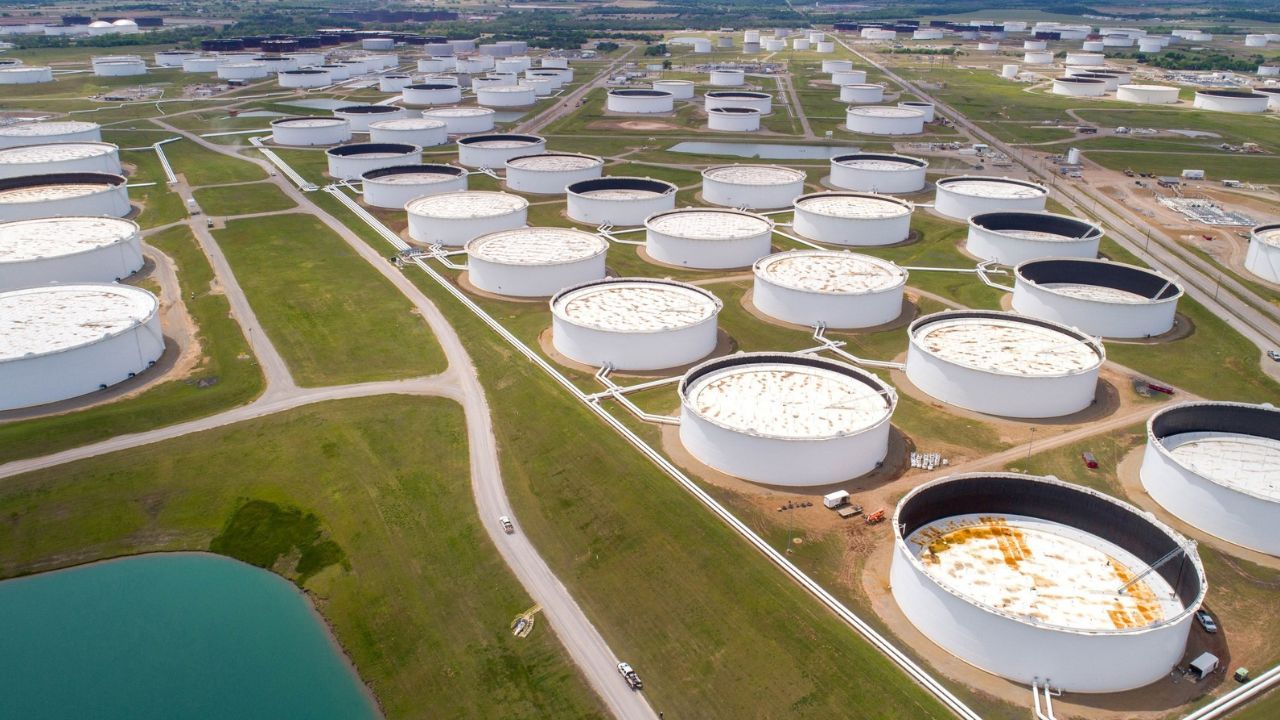
Brent crude, a widely followed international benchmark, settled at US$116.72 a barrel on October 23, up US$3.55, or 3.14%, for the day. US West Texas Intermediate settled at US$103.27, up US$3.80, or about 3.8%.
Concerns about disruption to Middle Eastern energy supplies helped drive the increase. The key point for everyday money is the price being attached to that uncertainty. No household needs to predict the next geopolitical development to understand why sustained expensive fuel would matter.
Crude oil is one input into your final bill
An international benchmark is not the price a Jamaican driver pays at a service station. Refining costs, shipping, exchange rates, taxes, distribution expenses and the timing of purchases all influence the retail amount. That makes it unsafe to translate Friday’s percentage move directly into next week’s petrol bill.
The same caution applies to electricity. The effect depends on the generation mix, fuel procurement arrangements and the rules governing charges in each country. A spike in crude can create upward pressure without producing an identical or immediate increase on every customer’s statement.
Still, sustained higher energy costs matter because fuel sits inside so many other prices. A business may pay more to transport goods, operate equipment or keep a premises running. Whether it passes those costs to customers depends partly on competition and how much room its profit margin provides.
Why Jamaica and its neighbours feel it differently
For fuel-importing islands, more expensive energy can mean a larger foreign-currency bill. The effect on any local currency depends on much more than oil, including tourism receipts, remittances, capital flows and policy. A higher oil price alone does not establish that devaluation is coming.
Energy-producing economies such as Guyana and Trinidad and Tobago face a different mix of opportunities and risks. Higher realised export prices can support revenue, but the benefit depends on production, contracts, costs and the timing of collections. Households in producing countries can still face higher prices for imported goods.
That difference matters when someone treats the Caribbean as one investment market. A fuel distributor, an airline, a hotel and an energy producer can have very different exposures to the same barrel of oil. The headline is regional; the earnings impact is company-specific.
The diaspora connection runs in both directions
Families in the United States and Canada may feel higher energy costs through commuting, heating or travel. If those expenses consume more disposable income, there may be less flexibility for savings or support sent home. That is a potential household-budget channel, not a measured decline in remittances.
Canada also has substantial energy production. Some businesses may benefit from stronger oil prices even while consumers face higher costs. A Canadian investment account and a Canadian household budget can therefore respond differently to the same market development.
For tourism-dependent islands, another channel is the cost of getting there. Airline fuel expenses can influence fares, but competition, hedging and booking demand also matter. It is too early to treat Friday’s oil settlement as evidence that Caribbean visitor arrivals will fall.
Investors need to look beyond the winning sector
An oil rally can make energy shares look attractive after prices have already moved. A beginner investor still needs to understand the company’s debt, operating costs, exposure to commodity prices and place within an existing portfolio. A strong commodity price is not a guarantee of a strong investment return.
For businesses that consume fuel, the important question is how much they can absorb or pass on. Watch for clear explanations of margins and costs in results. Revenue growth can look impressive while the amount left after expenses becomes less comfortable.
Higher energy costs can also complicate the inflation outlook. If price pressure spreads and persists, central banks may have less room to reduce borrowing costs. That is a possible policy response, not a forecast that any particular institution will raise rates at its next meeting.
What to watch without chasing every headline
The next useful signals are whether the higher crude price persists, whether actual supply disruption worsens and how local fuel and utility prices respond. Those observations are more useful for household planning than assuming that every intraday market swing will become a lasting change.
For now, the practical takeaway is to understand exposure. Transport-heavy businesses, families planning travel and households with little budget flexibility have different reasons to watch energy costs. Friday’s price is confirmed; the eventual effect on Caribbean bills and company profits is still unfolding.