

A Jamaican account kept open for decades can be more than a financial convenience. It can hold a house deposit, retirement plans and the promise of eventually spending more time at home. VM Group is now asking overseas Jamaicans to think about taking that relationship beyond savings and into investments.
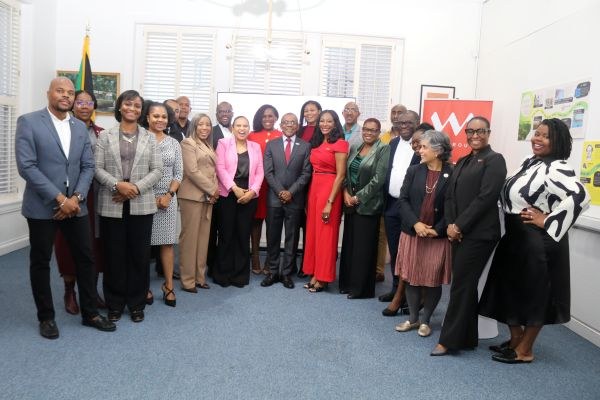
At an October 30 reception at the Jamaican Embassy in Washington, group president and chief executive Courtney Campbell described about 500,000 active accounts, including 109,000 held by overseas Jamaicans. He put the United States’ share of overseas accounts at about 55%, and said more than 60% of overseas members had maintained their accounts for over 20 years.
The outreach, which gained fresh diaspora coverage this weekend, promoted opportunities in property, stocks, bonds and business development. That is a broad menu. For a beginner investor, the important work starts with understanding that these choices do very different jobs—and that affection for Jamaica does not settle the financial questions.
A savings balance and an investment are different commitments
Savings generally serve money that must remain available for a planned payment or an unexpected expense. An investment accepts some combination of uncertainty, price changes or restricted access in exchange for the possibility of a return. Moving money between the two changes what the owner can rely on.
A stock represents ownership in a business. Its price can fall, and a dividend depends on the company’s capacity and decision to pay. A bond is a lending arrangement, with repayment dependent on the issuer and its terms. Property can generate rent, but repairs, vacancy and the time required to sell can materially change the result.
A product’s familiar brand does not make these risks identical. Nor does using a banking relationship mean that every investment offered alongside it has the same protections as a deposit. The account agreement, issuer, legal structure and applicable protection arrangements need to be understood separately.
For the diaspora, currency is part of the return
Someone earning US dollars in Florida or Canadian dollars in Toronto may evaluate a Jamaican investment in two currencies at once. The investment can gain in Jamaican dollars while delivering a weaker result when converted back into the currency used for rent, groceries or retirement abroad.
Consider a hypothetical investment that rises 8% in Jamaican dollars over a year. If, over the same period, one Jamaican dollar buys 5% less of the investor’s home currency, the combined return before fees and taxes is approximately 2.6%, rather than 8%. The calculation multiplies 1.08 by 0.95 and subtracts one.
That example is an illustration, not a currency forecast. Its purpose is to show why a headline return is incomplete. Conversion spreads, transfer charges and taxes can alter the result further. Conversely, money intended for future expenses in Jamaica has a different currency purpose from money needed for living costs overseas.
Property needs a budget after the purchase
Campbell also described overseas Jamaicans as representing approximately 30% of VM’s mortgage portfolio. That highlights the scale of the cross-border housing relationship, but it does not establish how profitable an individual property purchase will be. A mortgage helps finance an asset; it also creates an obligation that survives a disappointing rental month.
The useful property calculation starts with realistic rent and subtracts vacancy, maintenance, insurance, management, service charges and other recurring costs. Financing adds interest and principal payments to the cash-flow picture. A purchase that looks attractive before those deductions can require continuing support from an overseas salary.
Managing from another country introduces practical demands as well. Someone has to inspect work, collect rent, handle disputes and verify expenses. Written responsibilities and independent records become especially valuable when family members are involved. Trust helps a relationship; clear accounts help everyone understand the investment.
Rebuilding can create demand without guaranteeing profit
The Washington discussion also connected diaspora participation with Jamaica’s rebuilding needs, including housing, engineering, technology and small-business financing. These are real categories of economic activity. They are not interchangeable investment opportunities, and demand for a service is only one part of a business case.
A contractor can have a full order book and still run short of cash if customers pay late or material costs rise before a project is finished. A technology venture may need years of funding before generating reliable income. A small-business loan can expose the lender to a borrower’s entire operating risk.
For an overseas participant, useful questions include who owns the asset, who controls spending, how progress is documented and how money can eventually be withdrawn. The answers should be available before the transfer. A compelling national story cannot replace the terms of a specific transaction.
What should change after the sales pitch
The next meaningful evidence will be the actual products and projects offered: their fees, currencies, withdrawal rules, audited information and risk disclosures. Those details make it possible to compare alternatives on the same basis. A quoted yield without its conditions is an invitation to ask more questions.
VM’s overseas account base shows how durable Jamaica’s financial connection with its diaspora has become. Turning that connection into investment can support personal goals and productive activity at home. The test for each household remains concrete: what does the money need to do, what can go wrong, and what remains after every cost?