

Canada’s central bank governor has left the door open to another interest rate increase. For a household with a mortgage renewal coming up or relatives depending on money sent from Canada, the useful response is to work out which costs can change and when. A rate warning gives families time to check their numbers before the next decision.
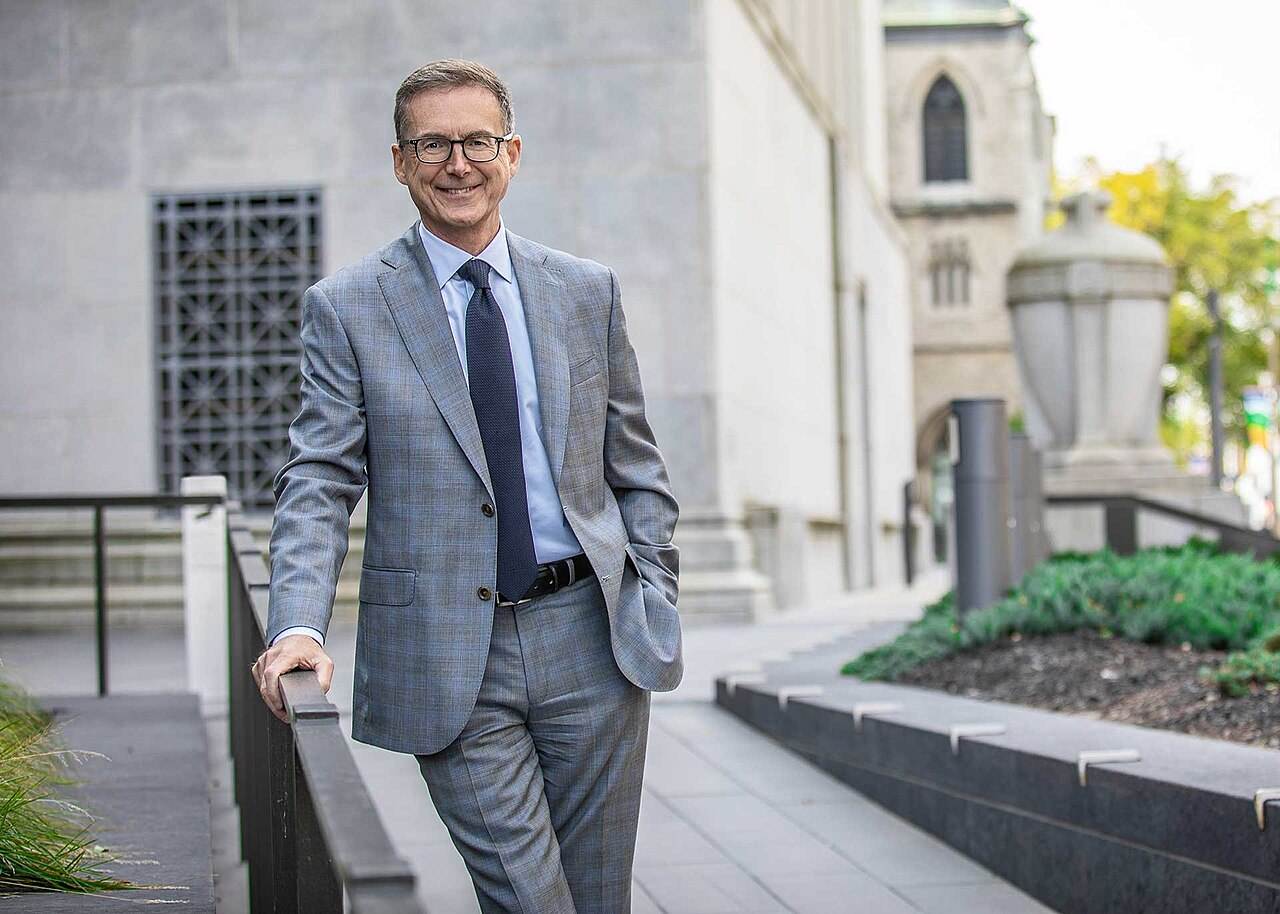
Speaking to a parliamentary finance committee on November 3, Governor Tiff Macklem explained why the Bank of Canada raised its policy rate from 2.25% to 2.5% on October 28 and why it might have to go further. The October move was its first increase since July 2023. The November appearance did not change the rate. Policymakers are assessing the outlook one meeting at a time, with the next decision scheduled for December 9.
Why an oil shock can change the cost of a loan
The Bank expects inflation to reach about 3.5% by year-end and stay at or above 3% through much of 2027. Those are projections. A key concern is that persistently expensive energy can spread from fuel bills into the cost of making and moving goods. A delivery business can absorb higher diesel costs for a while, for instance, but if they persist it may eventually raise prices.
Higher borrowing costs cannot produce more oil. They can cool demand by making credit more expensive, reducing the room businesses have to raise prices and discouraging a wider cycle of price increases. The challenge is timing. Move too slowly and inflation may spread; tighten too much and spending, hiring and investment may weaken. That balance is harder when new US tariffs are also weighing on Canadian activity.
For a household, the difference between a forecast and a bill matters. An inflation projection describes a broad basket of goods and services. It will not tell a particular family how much its weekly shop, insurance renewal or heating bill will rise. Families can see which costs matter most by looking at the bills they actually pay and separating regular spending from seasonal spikes.
Which borrowing costs can move first?
A variable rate loan or line of credit can respond sooner than a fixed rate mortgage. The exact effect depends on the lender and the contract. Some variable mortgages change the payment when rates change; others may initially allocate more of the same payment to interest. A fixed mortgage normally keeps its rate until the term ends. The financial pinch can arrive at renewal, even if the household felt no change after October’s decision.
An illustrative quarter-point increase on a C$300,000 balance amounts to C$750 more annual interest if the balance were unchanged and the full increase applied. That is about C$62.50 a month in simple interest, not a mortgage payment quote. Amortisation, compounding and the terms of the loan determine the actual payment. The exercise is useful because it turns a headline into a rough measure of how much room the budget has.
Households facing renewal can compare what happens if the available rate stays near today’s quote, moves higher or falls. Include any fees and repayment terms in the comparison. For savers, higher rates may make some deposits more attractive, while an existing fixed rate bond can lose market value when comparable yields rise. The same rate move can matter differently depending on whether you are borrowing, saving or selling an investment.
The exchange rate is a separate moving part
A Canadian rate increase does not guarantee that the Canadian dollar will buy more Jamaican dollars. US rates, oil prices, trade developments and investor demand for the US dollar can all influence currency markets. The transfer provider’s fee and exchange rate also affect what arrives. Compare the total Canadian dollars paid with the Jamaican dollars the recipient actually receives.
The family on the sending side matters too. If a Canadian household pays more to service debt, its ability to maintain a regular remittance can change even when the exchange rate moves in its favour. A household planning to send a fixed amount in Jamaican dollars may face a varying cost in Canadian dollars. Working from the recipient’s needs and the sender’s cash flow makes that risk easier to see.
Before December 9, the useful signals are whether inflation is broadening beyond energy, whether demand is holding up and how US trade restrictions affect jobs and exports. The next rate is undecided. What a household can know today is when its loans reset, how much a change could cost and how much of its budget crosses a currency border.